The Mechanics Behind Canada’s Productivity Deduction Framework
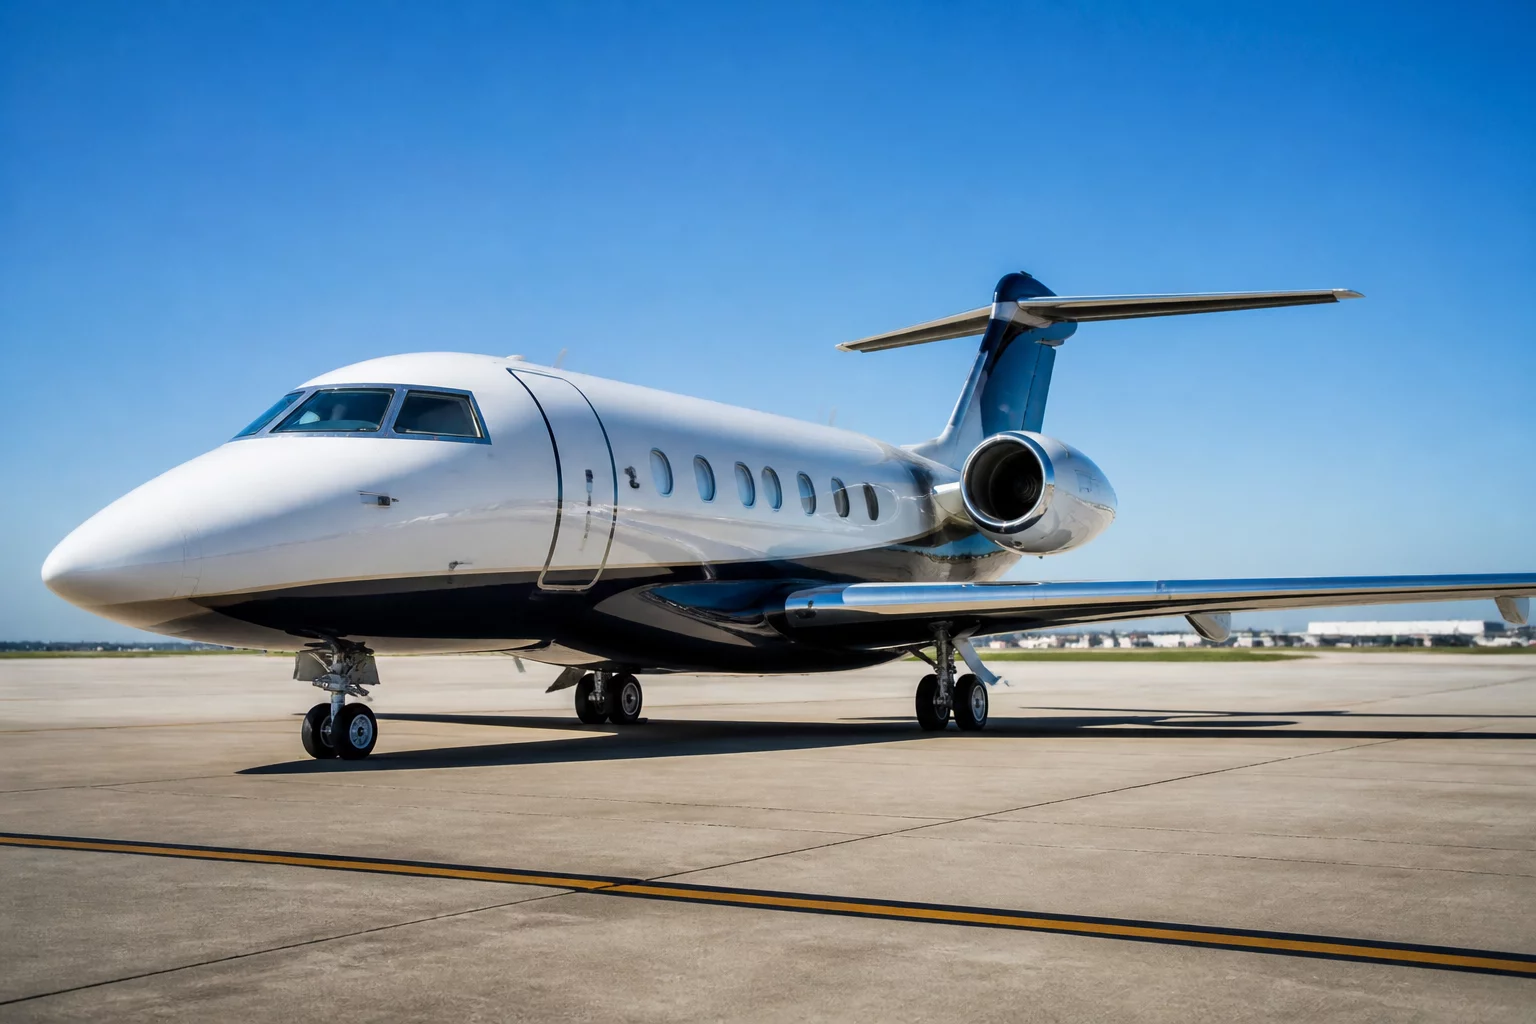
Under updated federal fiscal measures designed to stimulate direct corporate reinvestment into operational equipment, Canadian enterprises are applying enhanced Accelerated Investment Incentive provisions toward aviation assets. When structured in accordance with commercial travel mandates and inter-facility mobility guidelines, acquisitions of corporate aircraft can qualify for substantial initial-year write-downs. This regulatory alignment lowers the barrier of entry for multi-facility enterprises seeking direct air connectivity.
Rather than depreciating transport hardware across long schedules over fifteen or twenty years, corporations can now recognize early tax relief that preserves operational liquidity. For resource companies operating out of Calgary, manufacturing conglomerates based in southern Ontario, and engineering firms coordinating operations between Montreal and the northern territories, direct aircraft ownership has transformed from a discretionary balance-sheet item into a core productivity catalyst.
"Accelerated first-year write-offs have transitioned business aviation from an optional executive convenience into an active, high-return capital optimization strategy for Canadian enterprises."
— Marcus Thorne, Senior Aviation Tax Analyst
Market Repercussions Across Brokerages and FBO Operations
The downstream consequences of this tax policy are visible across Canadian aircraft brokerages, maintenance providers, and fixed-base operators. Pre-owned inventory levels for high-efficiency super-midsize jets and modern twin-engine turboprops have tightened significantly. Corporate acquisition teams are finalizing letters of intent more rapidly to ensure closing schedules conclude prior to fiscal year-end deadlines.
Concurrently, charter management firms are expanding fleet operations to onboard newly acquired corporate aircraft under private-commercial hybrid management programs. At primary business aviation centers such as Toronto Pearson, Billy Bishop, Calgary International, and Montreal-Trudeau, hangar space demand has outpaced existing apron capacities, triggering private capital investments into new maintenance facilities.
Core Factors Accelerating Aircraft Acquisitions
Corporate executive boards cite distinct logistical advantages that justify fleet modernizations under the current tax code:
- Direct access to secondary regional aerodromes without scheduled commercial feeder services.
- Substantial reduction in executive transit hours during multi-stop inter-provincial site inspections.
- Integration of next-generation engines that lower fuel burn, reduce operating noise, and support sustainable aviation fuel blends.
With corporate tax planning closely matching regional logistical realities, the Canadian business aviation sector continues to experience steady transactional momentum heading into 2027.
Dispatch Responses
No comments yet. Be the first to leave a response.
Leave a Response